13 Autopilot Expenses Worth a Second Look
When did you last read the details of a bill that pays itself? Autopay is a gift for busy lives. It keeps due dates from slipping and late fees away. It also means some charges run for years without anyone looking closely at them.
Streaming services get a lot of attention, but plenty of other costs renew on their own. Insurance, phone plans, bank fees, warranties, and auto-ship orders can all drift upward a little at a time. A short list of recurring expenses to review can turn those quiet charges back into choices you make on purpose.
This guide walks through 13 autopilot costs worth a second look, with a few ideas for each. It shares general ideas to think about, and it is not advice. Some of these bills affect your safety and protection, so the aim is to understand them, not to cut what matters. Take one at a time, at your own pace.
List Your Autopilot Bills in One Place
Download the free Money Reset Workbook and write down every recurring cost, so autopay stays helpful and never hides a surprise.
Get the Free Workbook1. Car insurance renewals
Car insurance often renews automatically, and the new price may be different from what you paid before. Renewal notices can be easy to skim and file away. Reading yours, even briefly, can show what changed.
Some people compare quotes from a few companies near renewal time. Others ask their current company about discounts they may qualify for. Coverage choices matter for your protection, so a licensed insurance agent can explain what each part of a policy covers before you change anything.
Find your next car insurance renewal date and add it to your calendar.
2. Home or renters insurance renewals
Home and renters policies also tend to renew without much notice. Over time, your home, your belongings, or your needs may change, while the policy stays the same. A yearly look can help the coverage still fit your life.
Some companies offer a lower price when you hold more than one policy with them. Others may cost less on their own. Rules and prices vary a lot by company and area. A licensed agent can explain options and what each choice would mean for your coverage.
Read the first page of your home or renters policy and note the renewal date.
A Small Reminder to Check In on Your Bills
Premier Print Works creates quality prints, mugs, and shirts for people who like to know where their money goes. Find a little nudge for your desk.
Visit Premier Print Works3. Cell phone plans
Phone plans change often, and the plan you chose years ago may not match how you use your phone today. Some people pay for more data than they use. Others pay extra fees each month because they go over.
Your monthly bill or account page usually shows how much data you use. Comparing that with your plan can show if a different plan might fit better. Some carriers offer lower cost plans that are not always shown up front, so asking is often a normal step. For related reading, see money management habits for more stability.
Check how much data you used last month and compare it with your plan.
“A bill that pays itself still deserves to be seen now and then.”
4. Home internet plans
Internet prices sometimes rise after an intro period ends, and the new price may stay in place for years. Speeds and plan names change too, so a plan that once made sense might now cost more than a faster one.
Looking at your bill can show the base price and any extra fees. Some people call their provider to ask about current plans or lower cost options. Some areas also have programs for households with lower incomes, and 2-1-1 (in the U.S.) can point people to local help.
Look at your internet bill and write down the monthly total and plan speed.
Track Every Recurring Cost on One Page
The free Money Reset Workbook gives you a clear page to note each autopay bill, its amount, and its renewal date.
Get the Free Workbook5. Monthly bank account fees
Some checking and savings accounts charge a monthly fee. Sometimes it can be avoided by meeting a condition, like a minimum balance or a direct deposit. If the condition changes in your life, the fee may start showing up again.
A careful look at a few recent statements can show any maintenance or paper statement fees. Some people ask their bank about accounts with fewer fees. Others look at local credit unions. Account rules and fees vary and change, so checking the details is a good habit.
Scan your last two bank statements for any monthly or service fees.
6. Credit card annual fees
Some credit cards charge a yearly fee. It is easy to forget about since it shows up only once a year. When it does appear, it can be a surprise.
Some people weigh the fee against the perks they actually use. If the perks are worth more to you than the fee, the card may still fit. If not, some card companies offer a no-fee version. Closing a card can affect credit in some cases, so it can help to learn more or ask the card company before deciding. You may also like money management tips for fixing your finances.
Check if any of your cards charge a yearly fee and note when it is due.
7. Extended warranties and protection plans
Protection plans are often offered at checkout for phones, appliances, and electronics. Some renew each month or year. Many people forget they have them until long after the item is gone.
Looking at your bank and card statements for small plan charges can turn up coverage for things you no longer own. Some items also come with a basic warranty from the maker. Reading what each plan covers can help you decide if it is worth keeping.
List any protection plans you pay for and the item each one covers.
8. Memberships and clubs
Warehouse clubs, roadside help, rewards clubs, and hobby groups often renew once a year. When you joined, it may have been a great fit. Over time, how often you use it can change.
One way to judge a membership is to look at how much you saved or used it since the last renewal. If the value still feels clear, it may be worth keeping. If not, you can let it lapse or switch to a lower tier where one exists.
Write down each membership you pay for and how often you used it lately.
9. Auto-ship and subscribe-and-save orders
Auto-ship orders send items like pet food, coffee, or vitamins on a set schedule. They can be handy and sometimes cost less. They can also pile up when you use things more slowly than the schedule.
Checking your pantry or closet for extra boxes can show if a delivery is coming too often. Many auto-ship programs let you skip a delivery or change the timing. Prices on auto-ship items can also change, so a quick look at the latest price may be worth it. Another place to look is budget templates for less stress.
Count the extra units you have of one auto-ship item at home.
10. Cloud storage and software plans
Storage plans, photo backup, and computer programs often bill monthly or yearly. They are easy to sign up for and easy to forget. Some people pay for the same kind of service more than once without noticing.
Looking at what each plan does can show if two overlap. Clearing out old files might also let you use a smaller, lower cost plan. Before canceling a storage plan, it is wise to save or move anything you want to keep.
Check how much of your cloud storage you are using right now.
11. Equipment rental fees on your bills
Some internet, cable, and other bills include a monthly rental fee for equipment, like a modem or a receiver. These charges are often small and listed in a long line of fees, so they can be easy to miss.
Some people choose to buy their own equipment, while others prefer to rent so the provider handles repairs. Both choices have trade-offs. Asking your provider what is allowed and what it would cost can help you compare.
Look for an equipment or rental line on your internet or cable bill.
12. Add-on services tucked into regular bills
Phone, utility, and service bills sometimes include extras, like device protection, premium support, or monitoring. Some were added on purpose. Others may have come with a promotion and stayed after it ended.
Reading each line on a bill can show what you are paying for. If an add-on no longer fits, the company can often remove it. Saving a note of the call or chat can help if questions come up later. For related reading, see budgeting habits for a stronger money plan.
Read every line on one monthly bill and circle any add-on you do not recognize.
13. Automatic reloads on toll, transit, and prepaid accounts
Toll accounts, transit cards, and some prepaid cards can reload on their own when the balance drops. The reload amount may have been set long ago and might be larger than you need now.
A quick look at your account settings can show the reload amount and how often it happens. Some people lower the amount so less money sits unused. If you move or stop driving a certain route, closing an old account may free up a balance. Rules vary, so the account terms are worth a glance.
Log in to one auto-reload account and check the reload amount.
Explore Our Top Picks for a Better Life
We have gathered the tools, resources, and products we think are genuinely worth your time, covering mindset, self-care, health, and home. All in one place, hand-picked to support a calm look at the bills that run on their own.
See Our Top PicksReal Stories, Real Results
Let me share two examples I like to use. Kezia set up autopay for every bill years ago and never looked back. One quiet Sunday she read through her bills line by line. She found a protection plan for a phone she no longer had and a rental fee for a modem she could replace. She told me that the changes were small, but it felt good to know exactly what she was paying for.
Daniel let his car insurance renew year after year without reading the notice. He finally opened it and saw the price had gone up. He called a licensed agent, asked questions about his coverage, and learned about a discount he had missed. He said that keeping good coverage mattered most, and the call helped him understand it better. Both of them said the same thing: autopay is helpful, and a regular look keeps it working for you.
Your Bills Can Run on Autopay and Still Feel Like Your Choice
Picture a calm hour once or twice a year where you open each autopay bill and read it with fresh eyes. You know what each charge is for and why you keep it. The bills still pay themselves, and you feel more at ease about every one.
Pick one expense from this list and give it a second look this week. Download the free Money Reset Workbook to list your recurring costs in one place. A little attention can keep autopay working in your favor.
Want Ready-Made Tools to Help You Put This Into Action?
Sometimes the fastest way forward is a tool that someone has already built. Browse our hand-picked resources and downloads, chosen to help you take the next step with less guesswork.
Browse Resources and Downloads
Ready to Give Your Bills a Second Look?
The free Money Reset Workbook helps you see every recurring charge clearly, so autopay keeps working for you.
Download Free Now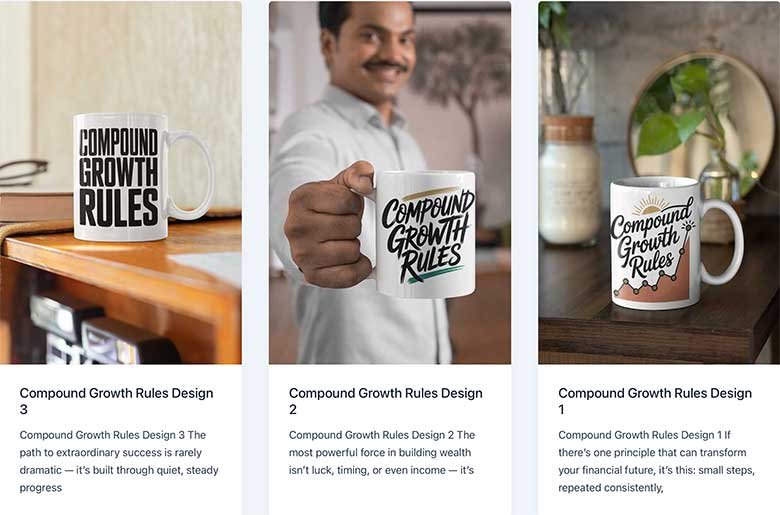
Bring Calm Money Habits Into Your Space
Premier Print Works makes quality prints, mugs, and shirts for people who keep an eye on the details. Browse the collection today.
Visit Premier Print WorksDisclaimer
The content on this page is for informational and inspirational purposes only. It is not professional financial, investment, tax, legal, insurance, or estate planning advice. Insurance coverage is important for your protection, so please talk with a licensed insurance agent before changing any policy. Prices, fees, and account terms vary and change, and rules for memberships, warranties, and accounts vary by company. Results vary widely from person to person. If money feels very tight, a nonprofit credit counselor or 2-1-1 (in the U.S.) may be able to point you to local help.
I am not a financial advisor, and I am not a licensed tax, legal, or investment professional. I share this information to help people learn about money and see new options. Please treat it as general information only, and talk with a qualified professional about your own situation before making financial decisions.
The stories of Kezia and Daniel are illustrative composite characters created to bring the content to life. They are not real people. Any resemblance to a real person is purely coincidental.
Some links on this page, including links to Premier Print Works and other resources, are affiliate links. If you make a purchase through one of these links, we may earn a small commission at no extra cost to you. We do not own, produce, or control any affiliate products, and we are not responsible for them — we only own and sell the products offered through our own store, Premier Print Works.
All content on A Self Help Hub is the property of Digital Marketing 215 LLC and is protected by copyright law. No part of this page may be copied, reproduced, republished, distributed, or transmitted in any form without prior written permission from the author.