13 Money Saving Ideas That Help You Grow Your Savings
I remember opening a savings account and feeling great about it. Then I didn’t touch it for months. I wasn’t avoiding it. I just forgot it was there until a statement showed up in the mail.
Researchers Dean Karlan, Margaret McConnell, Sendhil Mullainathan, and Jonathan Zinman tested whether that kind of forgetting matters. They ran field experiments with three banks, in Bolivia, Peru, and the Philippines. People who had recently opened commitment savings accounts were randomly chosen to get monthly reminders, some by text message and some by letter. The people who got reminders were more likely to reach their savings goals. Reminders that mentioned both savings goals and a financial incentive worked especially well.
Two other results stood out to me. Sending extra late reminders added nothing, and framing a message as a gain or a loss made no real difference. The researchers’ explanation is that people pay limited attention to big expenses that are coming later, so a reminder brings the goal back to the front of the mind. The boost was modest, and these were accounts in other countries, so I treat the findings as a hint and not a promise.
The 13 ideas below follow that thinking. A few come straight from the study, and the rest come from my own experience. I’ll tell you which is which as we go.
Give Your Savings Goal a Home on Paper
Grab my free Money Reset Workbook. It’s a good place to start writing your savings goal down.
Get the Free Workbook1. Give your savings goal a specific name
In the study, reminders that mentioned savings goals, along with a financial incentive, worked especially well. I take that to mean a goal in the message matters. “Save money” is easy to ignore. “New tires before winter” or “Dad’s birthday trip” is harder to ignore. The naming idea is my own extension.
Take a moment to rename your savings goal. A specific name is easier to picture, so a reminder has more to work with. Pick a name that makes you think of the thing itself, not the number.
Try this: Write your savings goal as a specific name, like “New tires in November.”
2. Write down why the goal matters to you
This idea is my own. A name tells you what you’re saving for, and a reason tells you why it matters. “So I never have to put a car repair on a credit card” is a reason that can carry you through a tight month.
Write your reason in one sentence and keep it where you’ll see it, like inside your banking app’s notes or on a sticky note on your desk.
Try this: Finish this sentence: “I’m saving for this so that ___.”
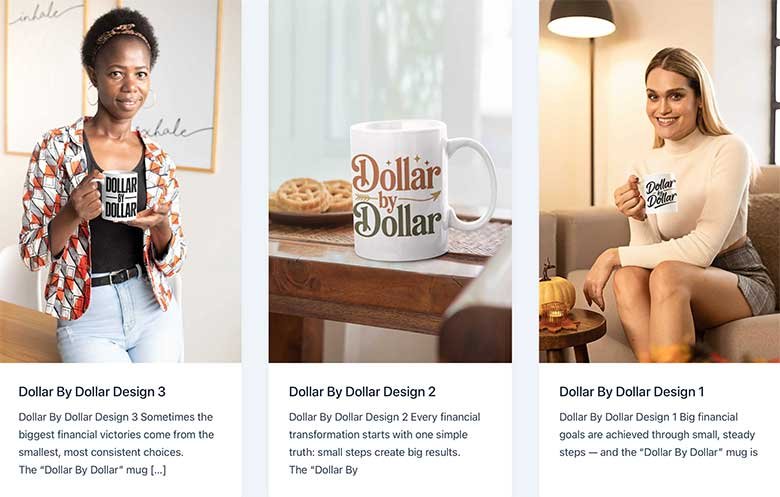
A Small Reminder of What You’re Saving For
I make prints, mugs, and shirts at Premier Print Works. Some people like a reminder where they can see it.
Visit Premier Print Works3. Set a reminder on payday to move money into savings
The study found that reminders increased the chance of reaching a savings goal. So give yourself one. Payday is a natural time, since that’s when you have money to move.
I’d set it for the day you get paid, or the day after. A reminder that shows up when money is available gives you something to do right then, instead of a wish for later.
Try this: Add a recurring reminder to your phone for every payday.
Sometimes the problem isn’t that you don’t want to save. It’s that the goal slipped out of sight.
4. Make the reminder mention your goal, not just the word “save”
In the experiments, messages that mentioned savings goals along with a financial incentive were especially effective. A reminder that says “Save $40” is a chore. A reminder that says “$40 toward the new tires” is a step toward something. That wording is my own.
Rewrite your payday reminder so it includes the goal’s name. It takes thirty seconds, and it’s the part of this article I’d do first if I could only do one thing.
Try this: Edit your payday reminder to include the name of your goal and an amount.
Take a Week to Think About What You’re Saving For
My free 7-Day Life Reset is a short week of reflection on your own routines. It’s a good place to start seeing what matters to you.
Start the Free Reset5. Use one good monthly reminder instead of a pile of them
The researchers found that extra late reminders didn’t help any further. I take that as permission to keep it simple. You don’t need five alerts a week. One clear message that arrives at the right time is enough.
I remember setting so many reminders on my phone that I started swiping all of them away. More isn’t better here. That part is my own experience, and it fits what the study found.
Try this: Look at your reminders and delete any that you always ignore.
6. Pair the reminder with an automatic transfer
A reminder works well when you still have to act. An automatic transfer takes the action out of your hands. Using both is a belt-and-suspenders approach that I like.
Set up a small automatic transfer for payday. Keep the reminder too, but let it serve as a check: did the transfer happen, and how is the goal doing? That’s my own method, not a finding from the study.
Try this: Set up a transfer for a small amount on each payday, even if it’s only $10.
7. Open a separate savings account for each big goal
Money that sits in checking tends to get spent. A separate account gives each goal its own home and its own balance. Many banks let you open a free savings account in minutes and give it a nickname.
Naming the account after the goal ties together the first few ideas. Every time you see “New tires” in your app, you get a little reminder for free. This is my own approach.
Try this: Open or rename one account after your most important savings goal.
8. Start with an amount that feels almost too small
I remember starting with $5 a week because I couldn’t face a bigger number. It felt pointless at first. But the habit stuck, and that mattered more than the amount.
A tiny amount you’ll keep doing beats a big amount you’ll stop. You can always raise it later. This one is from my experience and not from the study.
Try this: Pick an amount so small you can’t say no, and start it this week.
9. Raise the amount a little every few months
Once the habit is steady, nudge the number up. Add $5 or $10 every few months, or whenever you get a raise. Small increases hurt less than one big jump.
Put a reminder on your calendar for three months from now that says “Raise savings.” When it pops up, you can decide in one minute. That’s my own method.
Try this: Add a calendar note three months from today that says “Raise my savings amount.”
10. Put part of any windfall into savings
Tax refunds, bonuses, and gifts are chances to move your savings forward without touching your regular budget. You don’t have to save all of it. A slice is fine.
I remember a small refund that I was tempted to spend right away. I split it, with some for fun and the rest for savings. I didn’t feel deprived, and the savings got a real boost. That’s just my own approach.
Try this: Decide now what share of your next windfall will go to savings.
11. List the big expenses you can see coming this year
The researchers’ explanation is that people pay limited attention to large expenses that are coming later. So put them in front of yourself. Car registration, insurance premiums, holidays, school costs, and annual subscriptions all arrive on a schedule.
Write them down with their rough dates. Then you’ll know what you’re really saving for, and a reminder will have something specific to point to.
Try this: Write down three expenses you know are coming in the next twelve months and their approximate dates.
12. Check your savings balance once a month
Set a short monthly check. Open the account, look at the number, and compare it with where you hoped to be. It takes two minutes.
I remember avoiding a savings balance because I worried it was too small. When I finally looked, it was higher than I’d guessed, and that made me want to keep going. Looking beats guessing. That one is my own experience.
Try this: Pick a day each month to look at your savings balance, and set a reminder for it.
13. Celebrate milestones, then set the next goal
When you hit a goal, stop and notice it. Mark it somewhere, tell someone, or treat yourself in a small way. Then pick the next goal and give it a name.
Savings can feel like a long road with no scenery. Celebrating along the way keeps you moving. This is my own idea, and the next goal is what keeps the reminders meaningful.
Try this: Pick a milestone amount, and decide how you’ll celebrate when you reach it.
Explore Our Top Picks for a Better Life
I put together a list of tools and products I think are worth your time, covering mindset, self-care, health, and home.
See Our Top PicksTwo People Who Gave Their Savings a Name
I know a woman named Kezia who kept “saving for something” without ever getting anywhere. She renamed her account “Dad’s 70th Birthday Trip” and set a reminder on payday with that name in it. She told me that seeing the name every two weeks made it feel real, and she reached her goal a month early.
I also think about a guy named Daniel who was always surprised by his car insurance bill. He wrote down the year’s big expenses, found three he hadn’t planned for, and started a small monthly transfer for each one. He told me the bills still came, but they stopped feeling like emergencies.
Picture a Savings Goal You Can See
Imagine opening your banking app and seeing an account with a name you care about and a balance that’s growing. A reminder on payday nudges you, and the transfer goes through. The goal isn’t a fuzzy wish anymore. It’s something you’re visibly building.
Start with the first idea today. Give your goal a specific name. If you’d like a place to write it down, get my free Money Reset Workbook.
Want to Go Further?
I’m building out some deeper, paid resources for people who want more than a single article can cover. They’re not live yet, but you can see everything I currently have ready for you, free and otherwise, on my Top Picks page.
See What’s Available
Ready to Grow Your Savings?
Download my free Money Reset Workbook and put your savings goal in one place.
Download Free Now
A Small Reminder of What You’re Saving For
Take a look at Premier Print Works for prints, mugs, and shirts made for people who like a small daily reminder.
Visit Premier Print WorksDisclaimer
This page is for information only. It is not financial, tax, legal, insurance, investment, or estate planning advice. Everyone’s finances are different, so consider speaking with a qualified professional, such as a certified financial planner or a nonprofit credit counselor, before making major money decisions. The research referenced here comes from the published work of Dean Karlan, Margaret McConnell, Sendhil Mullainathan, and Jonathan Zinman, “Getting to the Top of Mind: How Reminders Increase Saving” (Management Science, 2016), summarized here in plain language. It involved field experiments with banks in Bolivia, Peru, and the Philippines, with people who had recently opened commitment savings accounts, and the boost it found was modest, so the results may not apply to everyone. The ideas labeled as my own are based on my experience, not on research. Results vary from person to person.
Kezia and Daniel are made-up characters used to bring this content to life. They are not real people.
Some links on this page, including links to Premier Print Works, are affiliate links. If you buy something through one, we may earn a small commission at no extra cost to you. We only own and sell products through our own store, Premier Print Works.
All content on A Self Help Hub belongs to Digital Marketing 215 LLC and is protected by copyright law. No part of this page may be copied or reused without written permission.