Retirement and Free Time: Filling New Hours Without Draining Savings
It is the first Monday with nowhere to be. The coffee tastes the same, but the day ahead feels wide open. By Wednesday, you have cleaned the garage, visited two stores, and had lunch out twice. It feels good, and it also feels like the money is moving faster than expected.
Retirement and free time arrive together, and for many people that is the best part. Yet open hours can quietly turn into spending. Shopping trips, meals out, new hobbies, and travel can all fill a day, and all can cost money. A little planning can help the new hours feel full without pulling too hard on savings.
This guide shares general information about that change, not advice. It leaves out investments, withdrawals, and benefits, since those are questions for a qualified professional. It is written with the United States in mind. Try one idea and see how it fits your new days.
Plan a Fun Budget for Your New Free Time
Download the free Money Reset Workbook to give outings, hobbies, and treats a planned place in your monthly budget.
Get the Free WorkbookNoticing how free time and spending connect
When work filled the day, many costs simply did not happen. There was less time to browse stores, eat out, or take short trips. Once those hours open up, spending can rise without any big decision behind it.
Some people track their spending for the first month or two of retirement just to see the pattern. Others look back at bank statements and compare them with their working months.
Noticing the pattern is not about cutting all the fun. It simply helps you choose where the money goes.
Look at your spending for the past month and circle anything tied to having more free time.
Giving fun its own line in the budget
Many retirees find it helpful to set a fun budget, a set amount each month for outings, hobbies, and treats. That way the fun is planned and guilt-free, and savings stay protected.
Here is an example with made-up numbers. Say lunch out twice a week costs about $18 each time. That is $36 a week, or $144 over four weeks. Knowing that number makes it easier to decide if it fits.
For related reading, see estimating retirement expenses.
Choose a monthly amount for fun and outings that feels comfortable.
A Little Something for Slow Mornings
Premier Print Works makes mugs, prints, and shirts for people enjoying a new chapter. Find one you like.
Visit Premier Print WorksA weekly rhythm can give open days some shape
Some people miss the structure work used to provide. A light weekly rhythm can help. Maybe Monday is for errands, Tuesday for a class, Wednesday for volunteering, and Thursday for friends.
A rhythm can also limit spending. If shopping happens on one set day, there are fewer unplanned trips during the rest of the week.
The schedule can be as loose as you like. Its purpose is to make the days feel your own, not to recreate a job.
Sketch a loose weekly rhythm with one main activity for each weekday.
“Open hours do not need to be filled with spending to be filled with something good.”
Low-cost and free activities are often close by
Libraries, parks, walking paths, community centers, and senior centers often offer free or low-cost activities. These might include book clubs, classes, exercise groups, game days, and talks.
Many places also offer discounts for older adults on things like movies, museums, and transit. A quick question at the counter is often how people find out.
Free events listed by your town or local paper can also fill a calendar without much cost.
Look up three free or low-cost activities near you.
See Your Monthly Spending at a Glance
The free Money Reset Workbook gives you simple pages to track spending and fun in your new routine.
Get the Free WorkbookVolunteering can fill time and connect you with others
Volunteering is one way to use free hours that costs little or nothing. Schools, food banks, animal shelters, libraries, and places of worship often welcome help.
It can also bring structure and new friendships. Some people volunteer once a week, and others pick projects now and then.
Before saying yes, it can help to ask about any costs, like travel, uniforms, or supplies, so there are no surprises.
Make a list of two or three places where you might like to volunteer.
Choosing hobbies with an eye on ongoing costs
New hobbies can be exciting. Some, like golf, boating, or certain crafts, come with high costs for gear, fees, and supplies. Others, like walking, reading, gardening from seed, or card games, cost much less.
One option is to try a hobby with borrowed or secondhand gear before buying new. Many communities have clubs where members share equipment or tips.
There is nothing wrong with a costly hobby you love. It may simply help to plan for it in your fun budget. Another place to look is saving money without giving up your lifestyle.
Write down the yearly cost of any hobby you are thinking about starting.
Planning bigger trips and projects ahead
Retirement often brings dreams of travel or big home projects. These can be wonderful, and they can also be the largest costs of the early retirement years.
Some people choose one bigger trip or project each year and save for it in advance. Others spread smaller trips across the year.
Writing down a rough cost and a save-by plan can help keep these dreams from surprising your savings. For related reading, see retiring comfortably on a budget.
Choose one trip or project you would love to do and write down a rough cost.
Sharing plans with a partner or family
If you share a home, the change to free time affects everyone. One person may want to travel while the other wants to stay home. One may spend more freely now that work is over.
A calm talk about how each person hopes to spend their time and money can avoid surprises. Some couples set a shared fun budget and a personal one for each person.
Family members may also have hopes about your time, like childcare. Talking openly about what you are glad to give can keep things kind on all sides.
Talk with your partner or family about how you each hope to spend your free time.
Checking in after the first few months
The early months of retirement can look very different from later ones. Some people spend more at first and then settle into a steadier pattern.
A short check-in after three to six months can show how spending and free time are lining up with your plans. You can adjust your fun budget or weekly rhythm as needed.
Questions about investments, withdrawals, or Social Security are best taken to a qualified professional. You may also like retirement planning mistakes some people run into.
Put a reminder on your calendar to review your spending and free time in three months.
Explore Our Top Picks for a Better Life
We have gathered the tools, resources, and products we think are genuinely worth your time, covering mindset, self-care, health, and home. All in one place, hand-picked to support the goals you are working toward.
See Our Top PicksReal Stories, Real Results
Let me share two examples I like to use. Amara retired from nursing and found herself shopping almost every afternoon just to get out of the house. She joined a library book club, started volunteering at a school, and set a monthly fun budget. She told me that her days felt fuller than ever, and her spending settled back down.
Joel wanted to take up boating after he retired. He wrote down the yearly costs and decided to join a friend’s club first. He also started walking each morning with a neighbor. Both of them said the same thing: planning how to spend their free time helped them enjoy it without worrying about their savings.
Full Days That Fit Your Savings
Picture a week with a book club on Tuesday, volunteering on Wednesday, lunch with a friend on Friday, and a fun budget that covers it all. Your days feel full, and your savings feel steady.
Start by setting a simple fun budget. Download the free Money Reset Workbook to plan your monthly spending around the life you want now.
Want Ready-Made Tools to Help You Put This Into Action?
Sometimes the fastest way forward is a tool that someone has already built. Browse our hand-picked resources and downloads, chosen to help you take the next step with less guesswork.
Browse Resources and Downloads
Ready to Enjoy Your Free Time With Confidence?
The free Money Reset Workbook helps you plan your days and your spending together, so your savings feel protected.
Download Free Now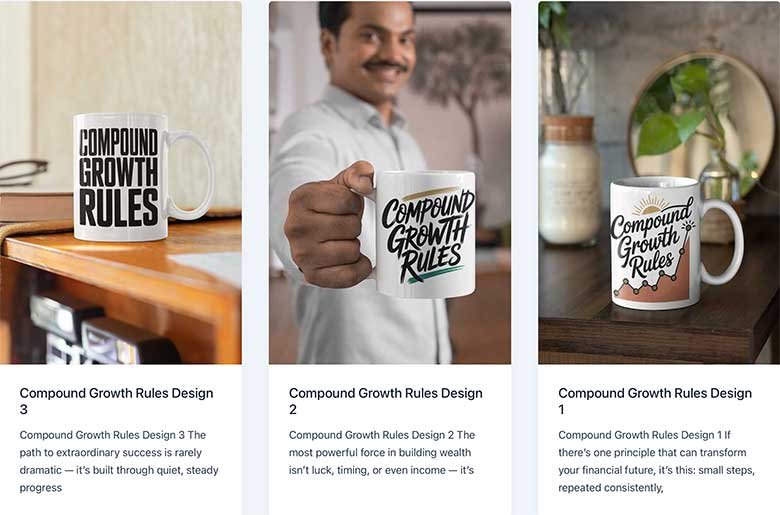
Celebrate the New Chapter
Premier Print Works creates quality mugs, prints, and shirts for retirees and new beginnings. Browse the collection today.
Visit Premier Print WorksDisclaimer
The content on this page is for informational and inspirational purposes only. It is not professional financial, investment, tax, legal, insurance, or estate planning advice. Nothing here is advice about investments, withdrawals, pensions, or Social Security, and nothing here is a recommendation to buy or sell anything. All investing involves risk, including the possible loss of principal. Please talk with a qualified professional about your own situation. This is written with the United States in mind. Prices, discounts, fees, and account terms vary and change. The numbers in the example are made up. Results vary widely from person to person.
I am not a financial advisor, and I am not a licensed tax, legal, or investment professional. I share this information to help people learn about money and see new options. Please treat it as general information only, and talk with a qualified professional about your own situation before making financial decisions.
The stories of Amara and Joel are illustrative composite characters created to bring the content to life. They are not real people. Any resemblance to a real person is purely coincidental.
Some links on this page, including links to Premier Print Works and other resources, are affiliate links. If you make a purchase through one of these links, we may earn a small commission at no extra cost to you. We do not own, produce, or control any affiliate products, and we are not responsible for them — we only own and sell the products offered through our own store, Premier Print Works.
All content on A Self Help Hub is the property of Digital Marketing 215 LLC and is protected by copyright law. No part of this page may be copied, reproduced, republished, distributed, or transmitted in any form without prior written permission from the author.