11 Money Saving Habits That Help You Prepare for Surprise Expenses
The check engine light comes on during your drive to work. By lunch, a mechanic is saying a number out loud, and your stomach drops.
If that scene feels familiar, you are far from alone. The Pew Charitable Trusts surveyed American households and found that about 60 percent had faced a financial shock in the past year, such as a major car repair, a medical bill, or a drop in income. The median cost of a household’s most expensive shock was $2,000, which was about half a month of income. A major car repair was the most common shock, reported by 30 percent of households. Families across income levels, races, and age groups experienced shocks at similar rates. Pew collected that survey data around 2014, and a later report found nearly the same pattern, so the details may have shifted, but the basic point has held up.
Here is the part that stayed with me. Among households that faced a shock, 47 percent also reported serious financial shortfalls that year, compared with 16 percent of households that had no shock. A surprise is usually not the end of the world. It is what happens next that matters, and these eleven habits are about getting ready for what happens next.
Know Your Numbers Before the Surprise Arrives
Download the free Money Reset Workbook and get a clear, simple picture of what comes in and goes out, so a surprise has less room to shake you.
Get the Free Workbook1. Write your own shock list, because your surprises are probably more predictable than they feel.
Pew found that car repairs were the most common shock, but your list may look different. Think about what is most likely to hit your household. Do you drive an older car? Own a home or rent? Have pets? Have a medical issue you keep an eye on? Does your income vary?
Write down your top five likely surprises. Do not make it a worry list. Think of it as a map. When a surprise is something you named in advance, it loses a little of its power to shock you.
As a category, surprises are quite predictable. Something will happen. You just cannot know which one, or when.
Write your top five most likely surprise expenses on a single page, and keep it somewhere you can find it.
2. Put a rough price on your most likely surprise, so you know the size of what you are preparing for.
Preparing for a vague “emergency” is hard. Preparing for a specific, priced one is easier. For your top item, find a ballpark number. Call a repair shop and ask what a typical brake job costs. Look up your health plan’s out-of-pocket maximum. Check what a vet visit would run.
You do not need an exact figure. A range is fine. Pew’s median of $2,000 can be a rough yardstick, but your own numbers matter more than a national median.
Once you have a price, your target becomes concrete. “I want $800 for a car repair” is much easier to work toward than “I should save more.”
Look up a rough price for your top surprise this week, and write it next to the item on your list.
Keep a Calm Reminder Close
Premier Print Works creates quality prints, mugs, and shirts for people building a steadier money life. Find a reminder that helps you stay prepared and calm.
Visit Premier Print Works3. Keep a small fund that is separate from your regular accounts, so it is ready when you need it.
A surprise does not wait for you to feel ready. Having even a small amount set apart can cover many smaller shocks, such as a tire, a co-pay, or a repair, without touching your bill money. It also gives you time to think instead of reacting.
Keep the money in a separate savings account, so it is easy to reach but not so easy that you tap it by habit. Starting small is fine. Even a few hundred dollars can change how a surprise feels.
Treat it like a bill you pay to your future self. A small, regular amount adds up over time.
Set up an automatic transfer, even a small one, into an account just for surprises.
“You cannot know which surprise is coming. You can know what you will do when it does.”
4. Know your deductibles and coverage before something happens, so the bill does not surprise you twice.
Insurance can turn a huge cost into a smaller one, but you usually pay a deductible first. That is the amount you cover before insurance helps. If your car deductible is $1,000, a $1,200 repair still costs you $1,000 upfront.
Look at your auto, health, and renters or homeowners policies. Write down each deductible and out-of-pocket limit on one page. If a deductible is much larger than your savings, you have found a gap worth knowing about.
I am not an insurance professional, so please ask your provider or a licensed agent about your specific coverage. The goal is simply to know your numbers ahead of time.
Make a one-page list of your insurance deductibles, and compare each one to your current savings.
Stay Steady When Life Surprises You
The free 7-Day Life Reset gives you a short, simple way to reset your week, which helps after a stressful surprise knocks you off course.
Get the Free Reset5. Keep up with regular maintenance, since small fixes often cost less than big breakdowns.
Many surprise expenses start as small problems we ignore. A worn tire, a leaky faucet, or a skipped dental checkup can grow into a much more expensive fix. Regular maintenance may be dull, but it often costs less than waiting for a breakdown.
Make a short list of the maintenance items you tend to put off, and put them on your calendar. Set a reminder for oil changes, filter swaps, and checkups. That way, you handle them on your schedule, not an emergency’s.
This habit will not prevent every surprise, but it can shrink the number of them.
Pick one maintenance task you have been putting off, and book it this month.
6. Make a who-to-call list now, so you are not searching for help in the middle of a crisis.
When a big bill arrives, many people feel stuck and frozen. A short list of who to call can help. Include your insurance company, your landlord, your utility companies, and the billing offices for your doctors or hospital.
Many providers and utilities have payment plans or hardship programs, but you often have to ask. Calling early, before a bill is overdue, usually gives you more options than waiting.
Keep the list with your key account numbers in a safe, easy-to-find place. A little organization can lower the stress of a surprise a great deal.
Write down the phone numbers for your insurer, landlord, and main utilities, and save them in one place.
7. Know a few ways to raise cash quickly, so one surprise does not force a bad choice.
Sometimes a surprise is bigger than your fund. It helps to have a short list of ways to raise money without borrowing at a high cost. You might sell items you no longer use, pick up extra shifts, or offer a skill for a few weekends.
Write the list when things are calm. Next to each idea, note how fast it could bring in money and how much you might expect. When you are stressed, a ready list is easier to use than a blank page.
I would rather you reach for a plan you made calmly than a very costly short-term loan. Some payday and title loans carry extremely high costs, so please look closely before using one.
List three ways you could raise a few hundred dollars within a couple of weeks, and keep the list handy.
8. Decide in advance how you will pay for a surprise, in what order, so you are not making it up on the spot.
A simple order might be: first, the emergency fund. Second, trimming a few flexible expenses for a month or two. Third, asking about a payment plan. Fourth, if you must borrow, choose the lowest-cost option you can find.
Having an order takes some of the panic out. You are following a plan, not deciding everything in a rush. Write it down, and share it with your partner or a trusted person if you have one.
You can change the order later, but having a draft is better than none.
Write a four-step plan for paying a surprise bill, and tape it inside a cabinet or save it in your notes.
9. Plan the recovery as well as the response, because the weeks after a shock can matter as much as the shock.
Pew found that nearly half of the families it surveyed had not recovered from their most expensive shock at the time of the survey, which for most people was at least six months later. A surprise leaves a trail. Savings are lower, bills may be behind, and stress lingers.
After a shock, set a short recovery plan. Decide how much you will put back into your fund each payday, and for how long. Check whether any bills need catching up. Give yourself a date for a quick review.
Remember that recovery takes time. Be patient with yourself, and keep the plan simple.
After your next surprise, write a three-line recovery plan the same day, while the details are fresh.
10. Keep your important papers and logins easy to find, so you are not hunting for them under stress.
A surprise often comes with paperwork: insurance cards, account numbers, receipts, and medical records. Searching for these when you are upset makes everything harder.
Choose one safe place, such as a folder, a binder, or a secure digital folder, and keep the basics there. Make sure a trusted person knows where to find it if needed. Protect any sensitive information, and do not share it casually.
This habit costs nothing, and it can save you hours at a hard time.
Set up one folder this week for your insurance papers, account numbers, and contacts.
11. Review your list twice a year and after big life changes, since your surprises change as you do.
A new job, a move, a baby, a new car, or a pet all change your list of likely surprises. What you planned for last year may not fit now.
Every six months, or after a big change, look at your list again. Update the prices, check your deductibles, and see whether your fund is keeping pace. It only takes a few minutes, and it keeps your plan alive instead of forgotten.
Think of it as a short check-up for your money.
Put a recurring six-month reminder in your calendar to review your surprise list and your fund.
Explore Our Top Picks for a Better Life
We have gathered the tools, resources, and products we think are genuinely worth your time, covering mindset, self-care, health, and home. All in one place, hand-picked to support a steadier money life.
See Our Top PicksReal Stories, Real Results
Let me share two examples I like to use. Amara had always dreaded surprise bills. When she wrote a short list of the five things most likely to go wrong, her old car topped it. She called a repair shop, got a rough price for the most common repair, and started a small fund aimed at that number. She told me the list was oddly calming. The fear had a shape and a size now.
Joel’s surprise came first. A medical bill landed in his mailbox, bigger than he expected. Before panicking, he followed the plan he had written down: check the fund, call the billing office, ask about a payment plan. They set up a monthly amount he could manage. Afterward, he wrote a short recovery plan to refill his fund. Both of them said the same thing: knowing the first step made the whole thing feel smaller.
Preparing for Surprises Is About Having a Plan, Not Predicting the Future
Picture the next surprise bill landing on your doorstep. You still wish it had not happened, but you know where to look first. There is a small fund, a short list of phone numbers, and a plan for what comes next. The surprise is smaller because you are ready for it.
Choose two or three habits from this list, and start with the shock list. Download the free Money Reset Workbook to see where your money goes now. A little preparation today can make a hard day much lighter.
Want Ready-Made Tools to Help You Put This Into Action?
Sometimes the fastest way forward is a tool that someone has already built. Browse our hand-picked resources and downloads, chosen to help you take the next step with less guesswork.
Browse Resources and Downloads
Ready to Be Less Shaken by the Next Surprise?
The free Money Reset Workbook helps you see your numbers clearly, so a surprise bill feels more manageable.
Download Free Now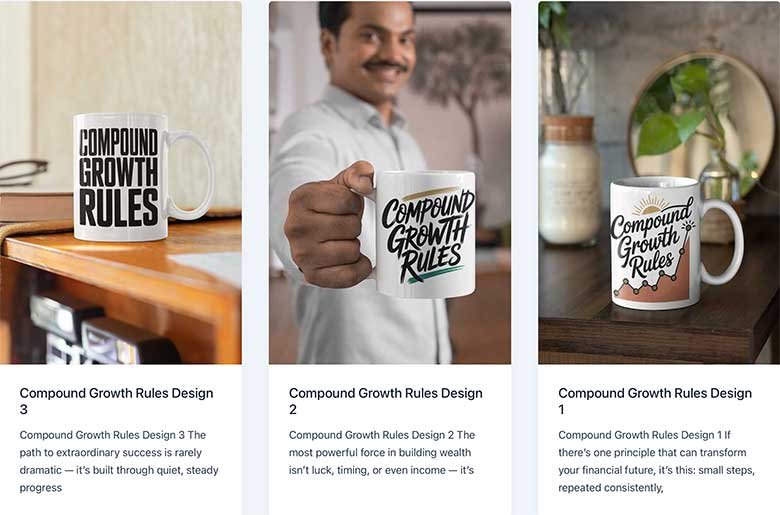
Fill Your Space With a Steadier Future
Premier Print Works makes quality prints, mugs, and shirts for people preparing for whatever comes. Browse the collection and find what speaks to your journey today.
Visit Premier Print WorksDisclaimer
The content on this page is for informational and inspirational purposes only. It is not professional financial, investment, tax, legal, insurance, or estate planning advice. Insurance coverage, deductibles, payment plans, and loan terms vary by provider and situation, so please check your own policies and consult a qualified professional before making decisions. Results vary widely from person to person. The survey data mentioned in this article was collected by the Pew Charitable Trusts around 2014 and 2015, and conditions may have changed since then.
The stories of Amara and Joel are illustrative composite characters created to bring the content to life. They are not real people. Any resemblance to a real person is purely coincidental.
Some links on this page, including links to Premier Print Works and other resources, are affiliate links. If you make a purchase through one of these links, we may earn a small commission at no extra cost to you. We do not own, produce, or control any affiliate products, and we are not responsible for them — we only own and sell the products offered through our own store, Premier Print Works.
All content on A Self Help Hub is the property of Digital Marketing 215 LLC and is protected by copyright law. No part of this page may be copied, reproduced, republished, distributed, or transmitted in any form without prior written permission from the author.