11 Budgeting Tips That Help You Give Every Dollar a Job
Payday arrives, and by the following Friday you cannot say where it went.
I have lived that blur. Money would come in on Friday and be gone by Wednesday, and I could not have told you where it went. The fix that helped me was not a complicated system. It was giving each dollar a job before the month started. When a dollar has a name, it is much harder to spend it on something else without noticing.
That is the idea behind the old phrase “give every dollar a job.” These eleven tips show you how to do it in a way that is simple, specific, and kind to yourself.
Give Every Dollar a Job, Starting With a Clear Plan
Download the free Money Reset Workbook and get a simple, ready-made way to assign each dollar of your income a purpose.
Get the Free Workbook1. Start with your income, and list every job it needs to do before the month begins.
Write down the amount of money you expect to receive this month. Underneath, list everything it needs to do: rent, utilities, food, transportation, debt payments, insurance, savings, and spending money. Use real amounts.
The goal is to account for every dollar before you spend it. When you plan ahead, you spend with a purpose, instead of finding out afterward where the money went.
If this feels like a lot, begin with the biggest items. You can add detail as you go.
Write down this month’s expected income, and list the five biggest jobs it must do.
2. Keep assigning dollars until the leftover is zero, so nothing is left without a purpose.
This is the heart of what people call a zero-based plan. Add up all your assigned jobs and subtract them from your income. If there is money left, give it a job. It might go to savings, to debt, to a goal, or to spending money.
Zero leaves room to save, because every dollar gets a name, including the ones you are saving. A dollar with no name tends to drift into whatever looks attractive.
If the total of your jobs is higher than your income, you have found a gap, and you can decide what to trim.
Add up your assigned jobs, and keep adjusting until income minus jobs equals zero.
Keep Your Money Purpose in Plain Sight
Premier Print Works creates quality prints, mugs, and shirts for people who give their money a purpose. Find a small reminder that every dollar can have a job.
Visit Premier Print Works3. Use specific names for your jobs, because vague labels invite loopholes.
Vague labels make a plan blurry. A category called “Stuff,” “Misc,” or “Extras” can absorb almost anything, and in my own budgets, that is exactly where money tends to disappear.
Rename your fuzzy categories with specific labels. Instead of “Fun,” try “Dinner out,” “Movies,” and “Hobby supplies.” A category called “Groceries” or “Car insurance” is much harder to bend.
Specific names also help later, when you review your spending.
Look at your categories, and rename any vague one with two or three specific labels.
“A dollar with no job tends to find one on its own, and it is rarely the one you would have picked.”
4. Write simple rules for what counts in each category, so you can skip the debate in the moment.
Is a coffee with a friend a food expense or a fun expense? Is a gift a household cost or a personal one? When the answer is unclear, it is easy to pick whichever category has room. I have caught myself doing exactly that.
Decide ahead of time. Write a one-line rule for the categories that tend to get fuzzy. For example: “Coffee out counts as Fun.” “Birthday gifts come from the Gifts line.” Deciding in advance keeps you from arguing with yourself at the checkout.
Keep the rules short and honest. If a rule keeps failing, change it, but do it on purpose, and never in the checkout line.
Write a one-line rule for the three categories you find hardest to keep clear.
Check In on Your Money Plan Each Week
The free 7-Day Life Reset gives you a short, simple way to look back at your week, which makes a weekly money check-in easier to keep.
Get the Free Reset5. Give your savings a named job, such as a goal with a name and an amount.
Savings is also a job. “Save money” is vague. “Car repair fund,” “Vacation,” and “Three-month cushion” are clear. Naming each savings pot makes it easier to protect.
Give your first savings job a small, reachable target. A buffer of a few hundred dollars is a realistic first goal, and it can keep a small surprise from turning into a big problem.
If your bank lets you create labeled sub-accounts, use them.
Name your top two savings goals, and give each a target amount.
6. Give irregular costs a monthly job, so yearly bills stop feeling like surprises.
Car registration, gifts, holidays, medical co-pays, annual fees, and repairs arrive a few times a year. If you do not plan for them, they can wreck an otherwise good month.
List your known irregular costs and estimate each one. Add them up, divide by twelve, and treat that as a monthly job. Set the money aside in a separate account or labeled pot.
When the bill arrives, the money is already there.
List five irregular costs from the past year, and calculate the monthly amount to set aside for each.
7. Give your fun money a job too, so you can spend it without guilt.
A budget with no room for enjoyment usually collapses. Assign a clear amount to personal spending, such as dining out, hobbies, and small treats. Give each adult in the household their own share if you can.
When the fun money is a defined job, spending it is part of the plan and nothing to feel guilty about. When it runs out, you know. That keeps fun from leaking into your essentials.
Make the amount realistic. Too small, and you will break the budget. Too large, and it will not leave room for your goals.
Set a clear monthly amount for fun money, and keep it separate from your other categories.
8. Decide in advance what happens to leftover money at the end of the month.
Sometimes you will finish the month with money left in a category. Without a plan, it often disappears into the next month’s spending. Give it a job.
You might decide that leftovers go to your emergency fund, a goal, or a debt. Or you might roll certain categories forward, like a gift fund. Write the rule down.
This keeps a small win from turning into a missed opportunity.
Write one sentence about where leftover money will go at the end of each month.
9. Share the plan with someone, since a little accountability keeps you honest.
Plans are easier to keep when someone else knows about them. A partner, a friend, or a trusted family member can play that role.
You do not need to share every detail. You can simply tell someone your main categories and goals, and agree to check in once a month.
If you share finances with a partner, make decisions together. A plan that you both helped design is easier to keep.
Choose one person to share your plan with, and schedule a monthly check-in.
10. Check in midmonth and move dollars on purpose, so the plan can bend without breaking.
Life changes during the month. A bill is higher, a plan changes, or a category runs out early. Do a short check around the middle of the month. See where each category stands.
If one is running short, decide where the money will come from. Take it from a lower-priority job, and write down the change. That way, you are adjusting on purpose, not drifting.
This also keeps small overspending from growing into a big problem.
Set a midmonth reminder to review each category and move dollars on purpose if you need to.
11. Look back at the month, and sharpen the jobs for next time.
At the end of the month, compare your plan with what really happened. Which jobs were accurate? Which were too big or too small? Which categories had loopholes?
Write a few lines about what you learned. Then adjust next month’s plan. Your first plans will be rough. Each month improves them.
Over a few months, you will build a plan that matches your real life.
At month’s end, write three lines about what worked, what did not, and what you will change.
Explore Our Top Picks for a Better Life
We have gathered the tools, resources, and products we think are genuinely worth your time, covering mindset, self-care, health, and home. All in one place, hand-picked to support a money plan that gives every dollar a purpose.
See Our Top PicksReal Stories, Real Results
Let me share two examples I like to use. Amara kept a category called “Misc” that somehow grew bigger every month. When she split it into four specific jobs, such as household items, gifts, pet care, and small treats, she saw that most of the growth came from one of them. She did not have to scold herself. She simply gave that job a limit and watched the number settle.
Joel’s challenge was a loophole of a different kind. He would call almost any purchase a work expense. He and Amara agreed on a short list of what counted, and they began a short monthly check-in. Joel told me that knowing someone would see the list changed his choices without any effort. Both of them said the same thing: clearer jobs, and a little accountability, closed the gaps.
Every Dollar Works Harder When It Has a Clear Job
Picture the first day of a new month with a plan in front of you. Every dollar has a name, your savings have goals, and your fun money is truly yours to enjoy. When a purchase comes up, you know which job it belongs to, and whether there is room.
Choose two or three tips from this list, and start by listing your income and its jobs. Download the free Money Reset Workbook to give each dollar a place on paper. Clear jobs make it much easier to feel in charge of your money.
Want Ready-Made Tools to Help You Put This Into Action?
Sometimes the fastest way forward is a tool that someone has already built. Browse our hand-picked resources and downloads, chosen to help you take the next step with less guesswork.
Browse Resources and Downloads
Ready to Put Every Dollar to Work?
The free Money Reset Workbook helps you see your numbers clearly, so every dollar has a clear job to do.
Download Free Now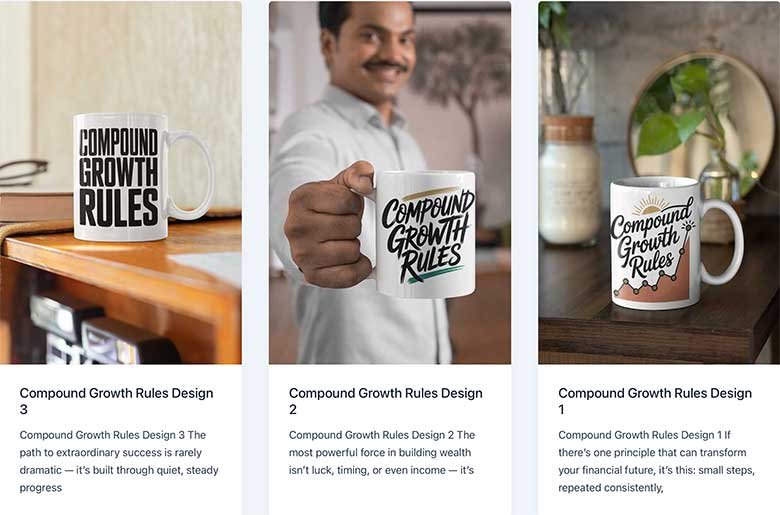
Fill Your Space With Money That Has a Purpose
Premier Print Works makes quality prints, mugs, and shirts for people who plan every dollar. Browse the collection and find what speaks to your journey today.
Visit Premier Print WorksDisclaimer
The content on this page is for informational and inspirational purposes only. It is not professional financial, investment, tax, legal, insurance, or estate planning advice. Income, bills, and account features vary, so please check the details of any account and consult a qualified professional before making financial decisions. Results vary widely from person to person.
The stories of Amara and Joel are illustrative composite characters created to bring the content to life. They are not real people. Any resemblance to a real person is purely coincidental.
Some links on this page, including links to Premier Print Works and other resources, are affiliate links. If you make a purchase through one of these links, we may earn a small commission at no extra cost to you. We do not own, produce, or control any affiliate products, and we are not responsible for them — we only own and sell the products offered through our own store, Premier Print Works.
All content on A Self Help Hub is the property of Digital Marketing 215 LLC and is protected by copyright law. No part of this page may be copied, reproduced, republished, distributed, or transmitted in any form without prior written permission from the author.