9 Budgeting Tips That Help Young Adults Give Every Dollar a Job
Your first real paychecks are exciting for about a week.
Then the rent, the phone bill, the loan payment, the groceries, and the weekend plans all start pulling at the same money, and it can feel like there is never enough to go around. Young adults often have a few extra challenges: an income that is new or uneven, shared costs with roommates, student loans, and a social life that is worth spending on.
I have always liked the idea of giving every dollar a job. When each dollar has a purpose before the month begins, it is much harder for money to vanish into nothing. These nine tips show you how to do it in a way that fits a young adult’s life. Keep it simple, and adjust as you learn.
Give Your First Paychecks a Plan
Download the free Money Reset Workbook and get a simple, ready-made way to give each dollar of your pay a clear job.
Get the Free Workbook1. Start with your take-home pay, since that is the money you can really use.
Many young adults build a budget from their salary or hourly rate, and then feel confused when the paycheck is smaller. Taxes and deductions come out first. Use the amount that actually lands in your account.
Add up what you expect to receive this month from all sources. If your pay changes from week to week, use the lower end of what you usually get, so the plan is realistic.
This number is the pot of money you will assign to jobs.
Write down your expected take-home pay for this month, using the lower end if your income varies.
2. List your must-pay bills first, so the essentials get their jobs before anything else.
Write down what you must pay each month: rent or your share of it, utilities, phone, transportation, insurance, minimum loan or credit card payments, and any other fixed costs. Include due dates.
These are the jobs that have to be done. Total them and compare with your take-home pay. If they take most of it, that is helpful to know. It shows you where your room to change things really is.
Check that you have not forgotten annual or occasional costs. They can sneak up on you.
Make a list of every must-pay bill with its amount and due date, and add up the total.
Keep a Reminder of What Your Money Is For
Premier Print Works creates quality prints, mugs, and shirts for young adults planning every dollar. Find a small reminder of your goals.
Visit Premier Print Works3. Give groceries, transportation, and other everyday costs a set amount, so they stop growing quietly.
After your fixed bills, you have costs that change from month to month, such as food, gas, and transit. Give each a specific amount based on what you really spend, not what you wish you spent.
Look at your last month or two of statements to find realistic numbers. If the totals do not fit in your pay, you will need to trim somewhere. Do it on purpose, instead of letting the account run dry.
Divide each amount by four to get a rough weekly number, so you can check yourself during the month.
Set a monthly and weekly amount for food and transportation, based on your past two months of spending.
“A dollar with a job is much harder to lose than a dollar left to wander.”
4. Give your social life its own job, so you can enjoy time with friends without guilt.
Being young often means spending on friends, events, and experiences. These matter, and a budget that ignores them usually falls apart. Give fun a clear amount each month.
When that money is gone, you know. You can choose cheaper ways to connect, like a potluck, a walk, or a game night. When there is still money in the pot, you can spend it without worry.
Be honest about what you enjoy. Spend more on the things that matter, and less on the things you barely notice.
Decide on a monthly amount for fun and friends, and keep it in its own category.
Check In on Your Budget Each Week
The free 7-Day Life Reset gives you a short, simple way to look back at your week, which makes a quick weekly money check easier to keep.
Get the Free Reset5. Handle shared costs with roommates in a clear, simple way.
Shared bills can cause stress if the system is vague. Agree on how you will split rent, utilities, internet, and groceries. Write it down. Use a shared note or a simple payment app to keep track.
Set a regular day each month to settle up. Pay your share on time, even if someone else is late, and talk kindly if there is a problem.
When you build your own budget, include only your portion of shared costs.
Write down how you and your roommates will split each shared cost, and agree on a settle-up date.
6. Give your student loans or other debts a clear job, and make sure the minimum payment is covered first.
If you have loans, list each one with its balance, interest rate, and minimum payment. Cover the minimums on all of them. Missing payments can lead to fees and hurt your credit.
If you have extra money, decide which debt gets it. Some people choose the highest interest rate to save the most money. Others choose the smallest balance for a quick win. Pick the one you will stick with.
If payments feel unmanageable, contact your lender or a nonprofit credit counselor. There may be options.
List your debts with their balances, rates, and minimum payments, and decide where any extra money will go.
7. Give savings a job before spending money gets a chance, and name it.
Savings should come out of the pot early. Choose a small amount to set aside each payday, and give it a name: “Emergency Fund,” “Car Repairs,” “Move Fund,” “Trip.” A named job is easier to protect than a vague “save money.”
Start small. A few dollars each payday adds up, and it builds the habit. Increase it when you can.
Use a separate account if possible, so the money is not mixed with everyday spending.
Name one savings goal, and set up an automatic transfer toward it for your next payday.
8. Plan for uneven income by budgeting from your lowest typical month.
If you work gig jobs, tips, or irregular hours, your income may swing a lot. Plan your budget around a low month, and treat anything above it as a bonus. When a strong month arrives, decide in advance how to use it.
A simple rule might be: half to savings or debt, half to enjoy. This keeps good months from being swallowed by spending.
Keep a little extra in checking if you can, to smooth out slow weeks.
Write down the lowest monthly income you have had in the last six months, and build your next budget around it.
9. Do a short check-in every week, and adjust without beating yourself up.
A budget is a plan, and real life will change it. Once a week, spend ten minutes checking where you stand. Look at each category. Are you on track? Do you need to move money?
If you overspend in one area, take it from another, and write down the change. That keeps you in charge.
At the end of the month, look back and note what worked. Your next plan will be better.
Put a ten-minute weekly money check on your calendar, and keep it going for a month.
Explore Our Top Picks for a Better Life
We have gathered the tools, resources, and products we think are genuinely worth your time, covering mindset, self-care, health, and home. All in one place, hand-picked to support the way you plan your money.
See Our Top PicksReal Stories, Real Results
Let me share two examples I like to use. Amara felt that her money disappeared each month, and she could not say where. When she gave each dollar of her take-home pay a job, with fixed bills first, then food and transportation, then fun, then savings, she saw that the leak was mostly weekend spending. She did not cut it. She gave it a set amount, and she felt freer to enjoy it.
Joel’s challenge was shared bills. His roommates were sloppy about splitting costs, and it caused tension. They wrote down who paid what and set a settle-up date each month. He said the arguments stopped, and his budget got more accurate. Both of them said the same thing: clear jobs for each dollar made money feel calmer.
A Young Adult’s Budget Works Best When Every Dollar Has a Clear Job
Picture the start of the month. Your pay has landed, your bills are covered, your fun money is set, and your savings are moving. You know what is left, and you know what each dollar is for. Surprises still happen, but they do not feel like disasters.
Choose two or three tips from this list, and begin with your take-home pay. Download the free Money Reset Workbook to give each dollar a place on paper. A simple plan beats a perfect one you never start.
Want Ready-Made Tools to Help You Put This Into Action?
Sometimes the fastest way forward is a tool that someone has already built. Browse our hand-picked resources and downloads, chosen to help you take the next step with less guesswork.
Browse Resources and Downloads
Ready to Put Every Dollar to Work?
The free Money Reset Workbook helps you see your numbers clearly, so every dollar has a job to do.
Download Free Now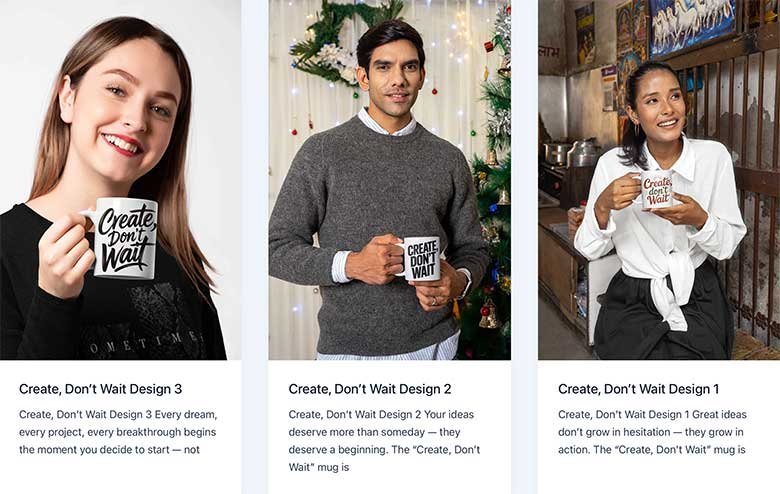
Fill Your Space With a Plan You Believe In
Premier Print Works makes quality prints, mugs, and shirts for young adults who budget with purpose. Browse the collection and find what speaks to your journey today.
Visit Premier Print WorksDisclaimer
The content on this page is for informational and inspirational purposes only. It is not professional financial, investment, tax, legal, insurance, or estate planning advice. Income, bills, loan terms, and account features vary, so please check the details of any account and consult a qualified professional or nonprofit credit counselor before making financial decisions. Results vary widely from person to person.
The stories of Amara and Joel are illustrative composite characters created to bring the content to life. They are not real people. Any resemblance to a real person is purely coincidental.
Some links on this page, including links to Premier Print Works and other resources, are affiliate links. If you make a purchase through one of these links, we may earn a small commission at no extra cost to you. We do not own, produce, or control any affiliate products, and we are not responsible for them — we only own and sell the products offered through our own store, Premier Print Works.
All content on A Self Help Hub is the property of Digital Marketing 215 LLC and is protected by copyright law. No part of this page may be copied, reproduced, republished, distributed, or transmitted in any form without prior written permission from the author.